
The real (inflation-adjusted) increase in China’s per capita GDP between 2018 and 2024 was, according to the official numbers also reported in World Bank/IMF statistics, 34 percent (an average rate of growth of almost 5 percent per year). When we look at Chinese household income surveys, whose scanty data (five quintiles with their average incomes) are published in China’s Statistical Yearbooks, that growth is almost perfectly matched: real per capita income in 2024 was 35 percent higher than in 2018. The inequality which can be calculated with such limited numbers is practically constant at 39 to 40 Gini points in all the years. Urban inequality is similarly unchanged, and rural inequality is up, mostly because of strong income growth among the top quintile of the rural population. But on the other hand, since rural incomes grew faster than urban, this counterbalanced pro-rich growth in rural areas and thus kept the overall inequality at an unchanged level. Thus the pictures painted by National Accounts (GDP numbers) and household surveys (income numbers) are quite consistent.
(It is worth mentioning that the “unchanged” inequality level that we calculate from the published data gives a Gini of 39-40. The official Chinese Gini which is based on the same surveys, and is presumably calculated across all micro data, is higher, at 46-47. It too is unchanged over the six-year period we consider here.)
The situation changes completely when we look at consumption data that also come from the large official household surveys. Consumption data are available with much greater detail thanks to the Chinese government supplying them to the World Bank in the form of percentiles (100 data points) every year for rural, urban and all of China. Such data, currently go only up to 2022, but, as I will show, the period 2018-22 is very differently depicted in consumption than income data. The tables below give a comparison.
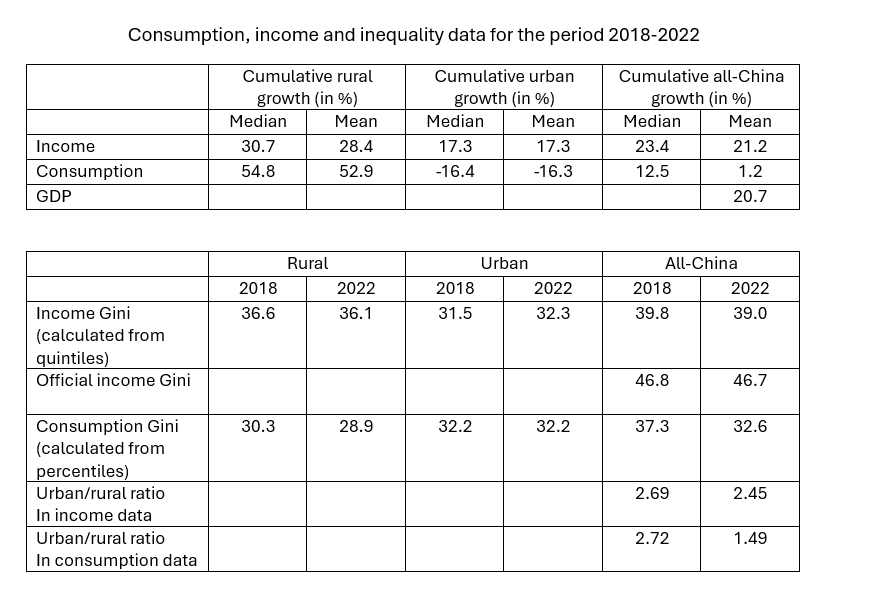
Urban consumption plummeted between 2018 and 2022: both at the median and the mean it was 16 percent lower than in 2018. Rural consumption, on the other hand, boomed, rising by more than 50 percent and shrinking in the process the urban/rural gap, calculated from consumption data, from 2.7 to about 1.5. Overall consumption Gini thus went down by almost 5 Gini points, which is an enormous decrease.
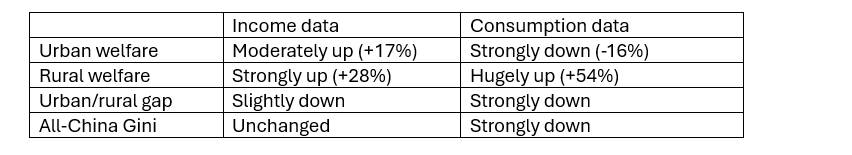
Now, this description of the changes is in total contradiction with what we can see from income data, both for the entire 2018-24 period, and for the subperiod 2018-22 (shown in the tables). According to income data, urban per capita real growth was +17 percent, not -16 percent (as consumption says). The increase in rural incomes was much more moderate than implied by the consumption data, urban/rural gap decreased only marginally, and the overall Gini was unchanged.
Let us summarize these major discrepancies.
How can we reconcile these results? What seems to have happened during the covid years is a huge shift away from urban to rural consumption. Looking at urban areas only, incomes continued growing while consumption went strongly down. Is it because under covid it was harder to consume, or because incomes were recorded in cities whereas people re-migrated to rural areas and consumed there? Or perhaps was it because urban people decided to save more than before? All three explanations, not only separately, but put together are possible. But the shift of consumption to the rural areas still did not fully compensate for the drop in urban consumption: the overall China-wide increase in consumption between 2018 and 2022 was a paltry 1.2%--in other words, per capita consumption was flat. But per capita incomes, as we saw, were not flat: they were rising.
Consider the consumption of the top urban percentile (the infamous top 1 percent). In 2022, in real (inflation-adjusted) terms it was less than in any year since 2015. In other words, in 2022, consumption of the richest urban percentile was back to the real level of seven years before. It was 20% lower than at the peak it reached before covid. The story is the same for the entire top urban decile. People consumed less, and since their earnings (it seems) did not decline, they must have saved much more.
Now, the top urban decile consumed in 2018 almost a third of all urban consumption in China. The consumption/GDP ratio, from National Accounts, was then about 40 percent. We also know that 80% of overall China’s consumption is in urban areas. This in turn means that urban people consumed 32 percent of China’s GDP (0.8x0.4), and a third of these 32 percent was consumed by the top decile. Let’s thus say that the top urban decile consumed 10-11 percent of China’s GDP. Since top decile’s consumption in 2022 was a fifth lower than in 2018, that means that the rich consumed about 2 percentage points of GDP less than we would expect them.
To go from this convoluted calculation to the conclusion: could it be that a significant part of China’s “consumption or wage compression” that we see in macro data is due to much greater savings of the urban elite? In other words, the issue behind the “compressed” or low consumption is not so much low social transfers or large state-sector corporate savings, but decisions of the elite to spend less and to save more. That decision does not seem to be driven by slower income growth among the urban rich. Although income data show them growing at slower pace than many others (including the rural rich), this is not comparable at all to what we observe in their consumption behavior: a very significant real drop.
Why are they saving more? Is it precautionary saving, greater availability of various domestic financial instruments, aging, transfer of money abroad (which compresses consumption at home), or possibly something else like overstated income in which case reduced consumption may be simply a reflection of lower income of the urban elite?
PS. Sources for this piece threefold: Chinese official distribution data published in various editions of the Statistical Yearbook, distribution data from the World Bank Poverty and Inequality Platform, and National Accounts.
I strongly agree with Prof. Milanovic’s reading of the data. A significant part of China’s unusually weak consumption over the past five years has indeed come from a sharp rise in the saving rate of the urban elite—not simply from inadequate social transfers, a low household share of national income, or excessive corporate savings.
But what caused this unusually sharp divergence between urban income and consumption?
The most important factor, in my view, is the negative wealth effect from the collapse in urban property prices.
Roughly 85% of China’s residential property wealth is concentrated in urban areas. Over the past five years, the value of urban residential property has fallen from roughly RMB 350 trillion to around RMB 250 trillion—a destruction of about RMB 100 trillion in household wealth, equivalent to almost two years of China’s total household consumption.
And the losses have been highly unequal.
For affluent urban households, property once accounted for as much as 65% of household wealth. When the value of the dominant asset on your balance sheet falls by one-third or more, consumption cannot remain unaffected even if your current income continues to rise.
The immediate household response is predictable: trade down in consumption, postpone discretionary spending, rebuild balance sheets, and raise precautionary savings.
This helps explain Milanovic’s most striking finding. The fall in consumption among China’s urban rich may have less to do with falling income than with a massive deterioration in perceived wealth.
China’s consumption problem over the past five years has therefore also been a balance-sheet problem.
My guess is the urban rich suppressed consumption to invest in residential real estate which turned out to be either very expensive consumption or wasted capital, depending on the point of view. Varying by city, real estate prices peaked between 2017-2022, and volume peaks after price, so it makes sense. Ratio of financial assets to income (household deposits, wmp, other financial instruments) didn't increase noticeably over this period. I remember one new concern bank analysts started having with China Merchant Bank (the leading retail bank) in 2018 was that "middle class" (200k-8mm rmb per account, this probably corresponds to the urban rich demographics in the world bank data) accounts growth was anemic whereas private bank (>8mm rmb, numbering in the low 10,000s) was strong. So it seems the percentiles data has some factual basis, though I question the magnitude of -16% decline, and the explanation is likely to be found in changes to non-financial investments, which for households are mainly real estate.